Tag Archives: wynne godley

Greg Mankiw And Empirics

Greg Mankiw wonders if teaching students empirics is feasible and answers in negative:

Noah Smith says introductory economics needs to be more empirical. I understand his argument, and have some sympathy with it, but I wonder if the substantial change he seems to be proposing is practical. Economists usually do empirical work with statistical tools that most college freshmen have not yet learned.

We teachers of introductory economics can and should explain where and why economists disagree. That is part of helping students develop their critical thinking skills. But I doubt students are in a position to try to evaluate the competing empirical work that shapes the differing views.

In the end, introductory economics is just that: an introduction to the economist’s way of thinking. That means giving students basic concepts–comparative advantage, supply and demand, market efficiency and market failure–that will make them more perceptive readers of the newspaper.

The failure to teach empirics to students and how it distorts their vision was well understood by Wynne Godley. In a 1993 article Time, Increasing Returns And Institutions In Macroeconomics, in S. Biasco, A. Roncaglia and M. Salvati (eds.), Market and Institutions in Economic Development: Essays in Honour of Paolo Sylos Labini, (New York: St. Martins Press), pp. 59-82 he wrote:

… But my objection goes beyond skepticism that the world we live in is being described realistically. My additional concern is that the NCP [neoclassical paradigm] is prejudicial with regard to the understanding of some of the most important processes going on in the world today. Thus in the ‘classical’ version of the NCP real output is determined by supply side alone; fiscal policy is entirely impotent and the government can only affect anything by changing the money supply; even then all it can do is affect the price level. The idea that fiscal policy is impotent, which seems to be based entirely on this model, has been extremely influential in contemporary political discussion; it is not just a provisional result suitable for a week or two in an elementary class.

Then the abolition of time prejudices the perception of inflation as an evolutionary process; the equilibria generate ‘explanations’ of price levels not changes, and theories of inflation cannot be convincingly coaxed forth. As if this were not enough, the whole construction leads by virtue of its axioms to the conclusion that wage and price flexibility, in combination with free trade, will generate full employment and convergence, if not equalisation, of living standards between countries and between regions within countries. In sum, while the absence of processes occurring in historical time means that the NCP does not encourage students to go and look up figures in books, if and when they are forced to do so their vision is likely to have been for ever distorted.

[emphasis added]

Steve Keen And Sectoral Balances

Steve Keen has a new article on sectoral balances here.

First apologies in advance for sometimes criticizing heterodox economists more but needless to say, such criticisms are of a totally different nature than criticisms of mainstream economists.

Anyway, I am surprised at why Keen mixes accounting identities, especially when it involves banks in the analysis. In the new article, Keen has an equation:

 Bank lending p.a. = Nominal GDP growth / Velocity of Money + Government Deficit + Trade Surplus

I don’t get this. The correct sectoral balances equation (in a simplified three-sector setting) is:

Net Lending = Government Deficit + Current Account Balance of Payments

Here, net lending is that of the private sector. The terminology net lending is something national accountants use, while Wynne Godley used NAFA  — net accumulation of financial assets which means a slightly different thing in national accounts, but this point is irrelevant here.

Keen’s equation seems to mix many things and it has a term for GDP growth which actually needs a model and is not something that can be derived from an accounting identity. Morever, Keen seems to forever blur bank lending and lending in general and hopefully he gets these things right in the future. The hidden assumption in Keen’s models —something which has been pointed out by Nick Edmonds — is that non-bank lending has no effect on aggregate demand which (the assumption) doesn’t make sense.

The original sectoral balances identity was used by Wynne Godley with a behavioural model around it, although he started building his models when he realized in the 70s that the accounting identity itself is a great revelation. And a narrative around the three balances makes a good story especially for telling a story about future scenarios and so on.

Keen, on the other hand has a relation which is not really an identity but a behavioural equation. By itself there’s nothing wrong but given his mixing things up, it really ends up adding confusions. Keen’s blog title uses the phrase “arithmetic” which simply means a manipulation of numbers but has an equation which is more than arithmetic. Reading his article suggests that he has improved the sectoral balances to take into account bank lending. But the sectoral balances equation is an identity even if banks exists. And Keen seems to derive his equation as if it were an accounting identity.

Again goes on to show, it is highly important in macroeconomics to know flow of funds properly.

Tobinesque Models

Paul Krugman writes today on his blog on James Tobin’s work:

Let me offer an example of how this ended up impoverishing macroeconomic analysis: the strange disappearance of James Tobin. In the 1960s Tobin developed and elaborated a sophisticated view(pdf) [original link corrected] of financial markets that offered insights into things like the role of intermediaries, the effects of endogenous inside money, and more. I’ve found myself using Tobinesque analysis a lot since the financial crisis hit, because it offers a sophisticated way to think about the role of finance in economic fluctuations.

But Tobin, as far as I can tell, disappeared from graduate macro over the course of the 80s, because his models, while loosely grounded in some notion of rational behavior, weren’t explicitly and rigorously derived from microfoundations. And for good reason, by the way: it’s pretty hard to derive portfolio preferences rigorously in that sense. But even so, Tobin-type models conveyed important insights — which were effectively lost.

Compare that to his article in response to another article on Wynne Godley which appeared in the New York Times – completely dismissing Godley’s work.

Three things: first Krugman claimed earlier that we needn’t look at old ideas:

But it is kind of funny to see a revival of old-fashioned macro hailed, at least by some, as the key to a reconstruction of the field

directly contradicting what he says today.

Second – obviously not having read Wynne Godley, he missed the point that Wynne’s analysis has significant improvement of James Tobin’s work.

Third, of course, Krugman’s understanding of monetary economics in general is poor, as can be seen when he gets into debates with heteredox economists and makes the most elementary errors. So it is strange he is lecturing others on this and fails once again to acknowledge heteredox economists.

Here’s Marc Lavoie describing in his article From Macroeconomics to Monetary Economics: Some Persistent Themes in the Theory Work of Wynne Godley in the book Contributions to Stock-Flow Modeling: Essays in Honor of Wynne Godley:

As Godley points out on a number of occasions, he himself owed his formalization of portfolio choice and of the fully consistent transactions-flow matrices to James Tobin. Godley was most particularly influenced and stimulated by his reading of the paper by Backus et al. (1980), as he writes in Godley (1996, p. 5) and as he told me verbally several times. The discovery of the Backus et al. paper, with its large flow-of-funds matrix, was a revelation to Godley and allowed him to move forward. But as pointed out in Godley and Lavoie (2007, p. 493), despite their important similarities, there is a crucial difference in the works of Tobin and Godley devoted to the integration of the real and monetary sides. In Tobin, the focus is on one-period models, or on the adjustments from the initial towards the desired portfolio composition, for a given income level. As Randall Wray (1992, p. 84) points out, in Tobin’s approach ‘flow variables are exogenously determined, so that the models focus solely on portfolio decisions’. By contrast, in Godley and Cripps and in further works, Godley is preoccupied in describing a fully explicit traverse that has all the main stock and flow variables as endogenous variables. As he himself says, ‘the present paper claims to have made … a rigorous synthesis of the theory of credit and money creation with that of income determination in the (Cambridge) Keynesian tradition’ (Godley, 1997, p. 48). Tobin never quite succeeds in doing so, thus not truly introducing (historical) time in his analysis, in contrast to the objective of the Godley and Cripps book, as already mentioned earlier. Indeed, when he heard that Tobin had produced a new book (Tobin and Golub, 1998), Godley was quite anxious for a while as he feared that Tobin would have improved upon his approach, but these fears were alleviated when he read the book and realized that there was no traverse analysis there either.

Draft link here.

On Models

Ryan Decker has a blog post on DSGE models. Although I don’t like DSGE models, I think he has something nice to say about modeling:

We must get econ pundits to understand that we’re all using models, including non-economist bloggers, even if they’re not written down as mathematical expressions. Writing a model down in its entirety so that its assumptions are made explicit and its internal workings can be examined by anyone is an act of intellectual humility. It is baffling to me that people who write down their models formally so we can all argue about them are supposedly worse and more arrogant than those who think they can identify a narrative model’s assumptions and keep it internally consistent.

James Tobin had something similar to say in his 1982 Nobel lecture Money and Finance in the Macroeconomic Process (alternative link):

Theoretical macroeconomic models of one brand or another are very influential. They guide the architects of econometric forecasting models. They shape the thinking of policymakers and their advisers about “the way the world works.” They color the views of journalists, managers, teachers, housewives, politicians, and voters. Almost everyone thinks about the economy, tries to understand it, and has opinions on how to improve its performance. Anyone who does so uses a model, even if it is vague and informal.

[emphasis added]

In his 1999 paper Money And Credit In A Keynesian Model Of Income Determination, Wynne Godley says:

This paper takes a step in the right direction by incorporating EM [endogenous money] ideas into a complete, if very much simplified model of the whole economy. Writings on monetary theory commonly rely solely on a narrative method which puts a strain on the reader’s imagination and makes disagreements difficult to resolve. The narratives in this paper will all describe simulations which are grounded in a rigorous model, which will make it possible to pin down exactly why the results come out as they do.

Personally I find stock-flow consistent models extremely useful to think about the working of the world as a whole. It is when you sit down and work through the models, that you realize how complicated the whole thing is and how naive intuition isn’t good enough. Of course models aren’t the only way to study, so one needs a mix of models and a non-mathematical narrative and some empirical analysis to add colour to the story. It is true models have disadvantages but beware of people who just highlight the disadvantages and don’t know the advantages because their intuition is also a naive model of the world.

Augusto Graziani, R.I.P.

Augusto Graziani has died.

One of Graziani’s main themes runs as follows. In order to finance production, the entrepreneur must obtain the funds necessary to pay his workforce in advance of sales taking place. Starting from scratch, he must borrow from banks, at the beginning of each production cycle, the sum which is needed in order to pay wages, creating a debt for the entrepreneur and, thereby, an equivalent amount of credit money, which sits initially in the hands of the labour force. Production now takes place and the produced good is sold at a price which enables the debt to be repaid inclusive of interest, while hopefully generating a surplus – that is, a profit – for the entrepreneur. When the debt is repaid, the money originally created is extinguished. An entire monetary circuit is now complete.

This account of the monetary circuit has a number of extremely important and distinctive features. It emphasises, in particular, that a) there is a gap in (historical) time between production and sales which generates a systemic need for finance; b) bank money is endogenously determined by the flow of credit and c) total real income must be considered to be divided into three parts – that received by entrepreneurs, that received by labour and that received by banks. We have already travelled an infinite distance from the (yes, silly) neo-classical world where production is (must be) instantaneous, where money must be exogenous and fixed and has no counterpart liability, and where the distribution of income is determined by the marginal products of labour and capital – a construction which depends entirely on the assumption that all firms sit perennially on a single aggregate neoclassical production function frontier.

− Wynne Godley, Weaving Cloth From Graziani’s Thread in Money, Credit And The Role Of The State: Essays In Honour Of Augusto Graziani

Some Nice Words On Wynne Godley And Monetary Economics

I am reading this book The Oxford Handbook of Post-Keynesian Economics, Volume 1: Theory and Origins and it has some nice chapters!

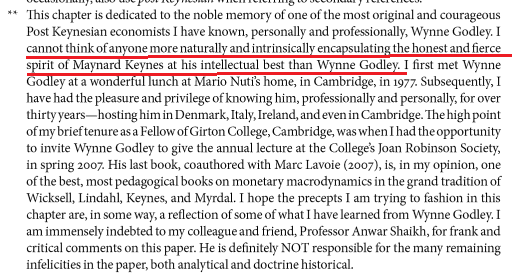
In his chapter Postkeynesian Precepts For Nonlinear, Endogenous, Nonstochastic, Business Cycle Theories, K. Vela Velupillai has some nice words on Wynne Godley and his book Monetary Economics co-authored with Marc Lavoie:

K Vela Velupillai On Wynne Godley(snipping via amazon.com)

Flow Of Funds And Keynesian Macroeconomics

The subject of money, credit and moneyflows is a highly technical one, but it is also one that has a wide popular appeal. For centuries it has attracted quacks as well as serious students, and there has too often been difficulty in distinguishing a widely held popular belief from a completely formulated and tested scientific hypothesis.

I have said that the subject of money and moneyflows lends itself to a social accounting approach. Let me go one step farther. I am convinced that only with such an approach will economists be able to rid this subject of the quackery and misconceptions that have hitherto been prevalent in it.

– Morris Copeland, inventor of the Flow Of Funds Accounts of the United States, in Social Accounting For Moneyflows, in Flow-of-Funds Analysis: A Handbook for Practitioners (1996) [article originally published in 1949]

Alas monetary myths continue to exist. The above referred handbook was published in 1996 starting with Copeland’s 1949 article and the editor of the book John Dawson himself had an explanation of why myths continue to exists despite some brilliant work such as that of Copeland. In page xx, Dawson says:

the acceptance of… flow-of-funds accounting by academic economists has been an uphill battle because its implications run counter to a number of doctrines deeply embedded in the minds of economists.

In a recent blog post blog post Paul Krugman is dismissive of Wynne Godley’s approach to macro modeling and instead appeals to some Friedmanism. Perhaps Dawson’s quote explains why this is so. However it may not be the only reason, given how Krugman has shown some tendency to be heteredox in recent times but his latest post ends all doubts and we can say he is highly orthodox. And that other reason is professional turf-defence.

Also, Krugman was writing in response to an NYT article Embracing Wynne Godley, an Economist Who Modeled the Crisis highlighting the importance of Wynne Godley’s work. That article was by a journalist who was perhaps unaware of the history of Post-Keynesianism. But Krugman himself dodged Godley’s work as “old-fashioned” – as if there is something fundamentally wrong about old-fashion and as if economics should proceed by one fashion after another.

A bigger disappointment is that Krugman failed to acknowledge that there has existed a heteredox approach since Keynes’ time. As Wynne Godley and Marc Lavoie begin Chapter 1 in their book Monetary Economics:

During the 60-odd years since the death of Keynes there have existed two, fundamentally different, paradigms for macroeconomic research, each with its own fundamentally different interpretation of Keynes’ work…

And Krugman’s usage of the phrase old-fashioned hides the fact that this is so.

Back to Copeland. In the same article Social Accounting For Moneyflows, Copeland is clear about his intentions and the direction he is looking:

When total purchases of our national product increase, where does the money come from to finance them? When purchases of our national product decline, what becomes of the money that is not spent? What part do cash balances, other liquid holdings, and debts play in the cyclical expansion of moneyflow?

Copeland’s analysis was not simply theoretical. It led to the creation of the flow of funds accounts of the United States and the U.S. Federal Reserve publishes this wonderful data book every quarter. Although, Copeland was simply looking and proceeding in the right direction, it can be said that a more solid theoretical framework to build upon Copeland’s brilliant work was still waiting at the time.

Of course, in the world of academics, there already existed two main schools of thought very hostile to one another. Keynes’ original work contained a lot of errors and for most economists, a bastardised version of Keynes’ work became the popular understanding. It was however the Cambridge Keynesians who founded the school Post-Keynesian Economics who believed they were true to the spirit of Keynes and this led to a parallel body of extremely high-quality intellectual work which continues to this day – and still dismissed by economists such as Paul Krugman. Of course, in this story, it should be mentioned that there was a Monetarist counter-revolution mainly led by Milton Friedman who was trying to bring back the old quantity theory of money doctrines and was “successful” in permanently distorting the minds of generations of economists to date. Greg Mankiw is quite straight on this and according to him, “New Keynesian” in the “New Keynesian Economics” is a misnomer and it should actually be New Monetarism.

Interestingly, one of Morris Copeland’s ideas was to show how the quantity theory of money is wrong. According to Dawson (in the same book referred above):

[Copeland] himself was at pains to show the incompatibility of the quantity theory of money with flow-of-funds accounting.

Meanwhile, in the 1960s and to the end of his life, James Tobin tried to connect Keynesian economics with the flow of funds accounts. While a lot of his work is the work of a supreme genius, he couldn’t manage. Perhaps it was because of his neoclassical background which may have come in the way. According to his own admission, he couldn’t connect the dots:

Monetary and financial data, so far as they are based on institutional balance sheets and prices in organized markets, are abundant. Modern machines have made it possible to improve, refine and expand the compilation of these data, and also to seek empirical regularities in financial behavior in the magnitude of individual observations. On the aggregate level, the Federal Reserve Board has developed a financial accounting framework, the “flow of funds,” for systematic and consistent organization of the data, classified both by sector of the economy (households, nonfinancial business, governments, financial institutions and so on) and by type of asset or debt (currency, deposits, bonds, mortgages, and so on). Although many people hope that this organization of data will prove to be as powerful an aid to economic understanding as the national income accounts, this hope has not yet been fulfilled. Perhaps the deficiency is conceptual and theoretical; as some have said, the Keynes of “flow of funds” has yet to appear.

– James Tobin in Introduction (pp xii-xiii) in Essays In Economics, Volume 1: Macroeconomics, 1987.

After having written a fantastic book Macroeconomics with Francis Cripps in 1983 and which has connections with the flow of funds, Wynne Godley thought he had to try hard to unify (post-)Keynesianism and the flow of funds approach which James Tobin was trying. Wynne Godley had the advantage of being close to Nicholas Kaldor who very well understood the importance of Keynes and was himself an economist of Keynes’ rank. Godley also had the advantage of having worked for the U.K. government and doing analysis using national accounts data and advising policy makers. Wynne Godley is the Keynes of “flow of funds” which Tobin was talking about!

A recent blog post by Matias Vernengo on Wynne Godley is extremely well-written.

In his later years (and his best), Wynne Godley worked with Marc Lavoie, one of the faces of Post-Keynesianism and one who had previously made highly original contributions to Post-Keynesianism and this led to the book Monetary Economics. Marc’s earlier work was also highly insightful and he highlighted – in the spirit of Morris Copeland – how poorly money is understood by economists in general and it was natural he and Wynne would meet and work together.

One of the things about Wynne Godley’s approach is how to combine abtract theoretical work and direct practical economic issues. This actually led him to warn of serious deflationary consequences of economic policy in fashion before the crisis.

Lance Taylor (in A Foxy Hedgehog: Wynne Godley And Macroeconomic Modelling) had a nice way to describe Wynne Godley:

Wynne has long been aware of the stupidity of models when you ask them to say something useful about practical policy problems. He has spent a fruitful career trying to make models more sensible and using them to support his policy analysis even when they are obtuse. As we have seen, this quest has led him to many foxy innovations.

But there is an enduring hedgehog aspect as well. Wynne has focused his energy on combining the models with his acute policy insight based on deep social concern to build up a large and internally coherent body of work. He has disciples and is widely influential. One might wish that he had pursued some lines of analysis more aggressively and perhaps put a bit less effort into others. And maybe not have written down so damn many equations. But these are quibbles. His work is inspiring, and will guide policy-oriented macroeconomic modellers for decades to come.

In this post, I have tried to provide the reader with references to go and verify how flow of funds1 cannot be separated from Keynesian Economics – Keynesian approach in the original spirit of Keynes, not some bastartized versions. It is as if they were made for each other2. While it is true that like other sciences, Macroeconomics is always work in progress, it doesn’t mean one should bring fashions such as inter-temporal utility maximising agents (read: future knowing economic actors) in the approach which Paul Krugman prefers.

1My usage of “flow of funds” is more generic than the usage which distinguishes income accounts and flow of funds accounts and hence my usage is for both.

2The ties between the flow of funds approach and Post-Keynesiansism is argued in Godley and Lavoie’s book Monetary Economics from which I have borrowed a lot.

Correction

I am mistaken about Jonathan Schlefer’s background. He is in academics.
The Rate Of Saving In Wynne Godley’s Models

In Krugman’s blog post which is dismissive of Wynne Godley’s work (referred in my previous post) he (Krugman) makes the following claim:

First involved consumption spending. Conventional Keynesian consumption functions suggested that the savings rate would rise as incomes rose — and this wasn’t just the Keynesian interpreters, Keynes himself made the same claim.

which shows that Krugman has less clue about what he talks. Funny, the profession is ruled by clowns like him.

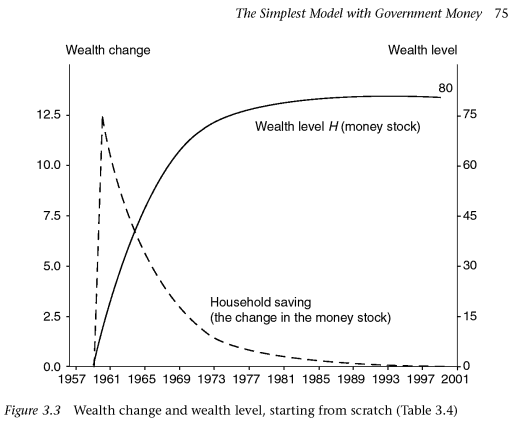
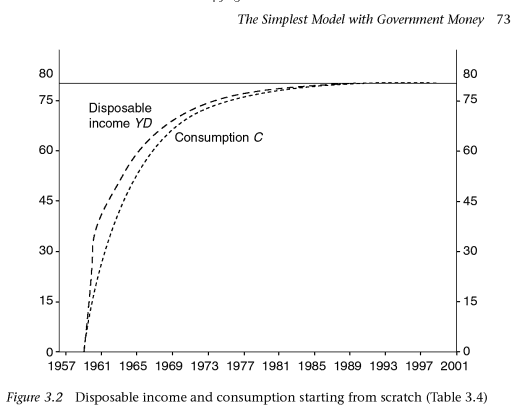
In Wynne Godley’s models, there is a propensity to consume out of income and out of wealth – represented in his models by the parameters α1 and α2 and the rate of saving in any period is given by the model. So in the simplest model – for example in Godley’s book with Marc Lavoie Monetary Economics, the rate of saving can has the following dynamic:

Disposable Income - G&L

Rate Of Saving - G&L

(image screenshot via amazon.com “Look Inside”)

(Note: In the above model, money is the only asset). This is starting from scratch but similar behaviour can be seen if one starts with some initial self-consistent configuration.

This is contrary to what Paul Krugman claims of Keynesian models. The above shows how the rate of saving first rises and then starts to fall and this whole adjustment will happen with a time lag given by a “stock-flow norm” and can be fast.

The reason it happens is simple. It is clear Krugman doesn’t realize the underlying stock-flow dynamics. As households’ saving and income rises because of a rise in government expenditure, they are also accumulating wealth. So a scenario where saving rises forever is meaningless because they would start consuming from their wealth as well.

Krugman continues:

This, in turn, led to predictions of rising savings rates after World War II, and hence a persistent shortage of demand — hence the secular stagnation theory briefly prominent. (There was even an early Heinlein novel built in part around the secular stagnation theory. As I recall, it was pretty bad.)

which is quite wrong – as stock-flow consistent dynamics suggests otherwise.

I’ll hold it to make any generic statements but it is clear that Krugman doesn’t know a thing or two about Keynesian Macroeconomics 🙂

*Many times standard textbooks use a Keynesian consumption function of the form

C = α0 + α1·YD

where C is the consumption, and YD is the disposable income.

It is then easy to see that C/YD decreases with YD and this is what Krugman is talking of.

However only slight improved modification where the consumption function depends on wealth as well leads to a different behaviour as highlighted in the main text. So it is strange Krugman dismisses consumption functions and instead talks of “failures that it seemed could have been avoided by thinking more in maximizing terms” !

*I thank Nick Edmonds in pointing this out.

Wynne Godley: The Keynes Of Flow Of Funds

Monetary and financial data, so far as they are based on institutional balance sheets and prices in organized markets, are abundant. Modern machines have made it possible to improve, refine and expand the compilation of these data, and also to seek empirical regularities in financial behavior in the magnitude of individual observations. On the aggregate level, the Federal Reserve Board has developed a financial accounting framework, the “flow of funds,” for systematic and consistent organization of the data, classified both by sector of the economy (households, nonfinancial business, governments, financial institutions and so on) and by type of asset or debt (currency, deposits, bonds, mortgages, and so on). Although many people hope that this organization of data will prove to be as powerful an aid to economic understanding as the national income accounts, this hope has not yet been fulfilled. Perhaps the deficiency is conceptual and theoretical; as some have said, the Keynes of “flow of funds” has yet to appear.

– James Tobin in Introduction (pp xii-xiii) in Essays In Economics, Volume 1: Macroeconomics, 1987.

[bolding: mine]

Paul Krugman writes in his blog responding to a recent Times article on Wynne Godley with a dismissive tone with mischaracterisation on saving etc. He writes:

But it is kind of funny to see a revival of old-fashioned macro hailed, at least by some, as the key to a reconstruction of the field.

Strange. First it is the story of a journalist from NYT who presented it the way it was. The NYT article was fine – what more can we ask from the journalists? But the funny thing is Krugman’s blog post itself which appeals to Friedmanism. Even funnier is the fact that Paul Krugman himself has turned to Keynesianism in recent times and talks about Michal Kalecki but when it suits his purpose, he dismisses Godley’s ideas as old fashioned!

Paul Krugman in his debates with heteredox economists has been exposed with his poor understanding of the nature of money. Wynne Godley’s approach on the other hand goes into a detailed look at the nature of money using the flow of funds among other things in a Keynesian way.

Now Krugman’s post is hardly a critique of any sort to deserve a response. But I thought quoting James Tobin is a good way to advertise Wynne Godley’s work because he has achieved what Tobin dreamed of and could not do it himself.

Also Wynne’s own idea about his work and aims can be seen from his writing in his article Keynes And The Management Of Real National Income And Expenditure, (in Keynes And The Modern World, ed. George David Norman Worswick and James Anthony Trevithick, Cambridge University Press, 1983):

… I have been forced to the conclusion that Keynes was a long way from achieving a coherent theoretical basis for maintaining them [correct ideas], and largely for this reason, his ideas have proved very vulnerable to the attacks from many different directions to which they have been subjected, particularly in the last fifteen years.

Wynne Godley’s work lays the foundation for Keynesian Economics. And Wynne Godley is the Keynes of flow of funds.

Correction: I am mistaken about Jonathan Schlefer’s background. He is in academics.
NYT On Wynne Godley

There’s a nice new article on Wynne Godley today in The New York Times.

An interesting thing in the article is the mention of intuition via models while mentioning his book Monetary Economics.

Why does a model matter? It explicitly details an economist’s thinking, Dr. Bezemer says. Other economists can use it. They cannot so easily clone intuition.

That is so right. The models in the books of Wynne Godley – both Monetary Economics with Marc Lavoie and Macroeconomics with Francis Cripps give a good idea about the authors’ intuitions. Of course, needless to say the man was bigger than his models.

Wynne Godley - NYT