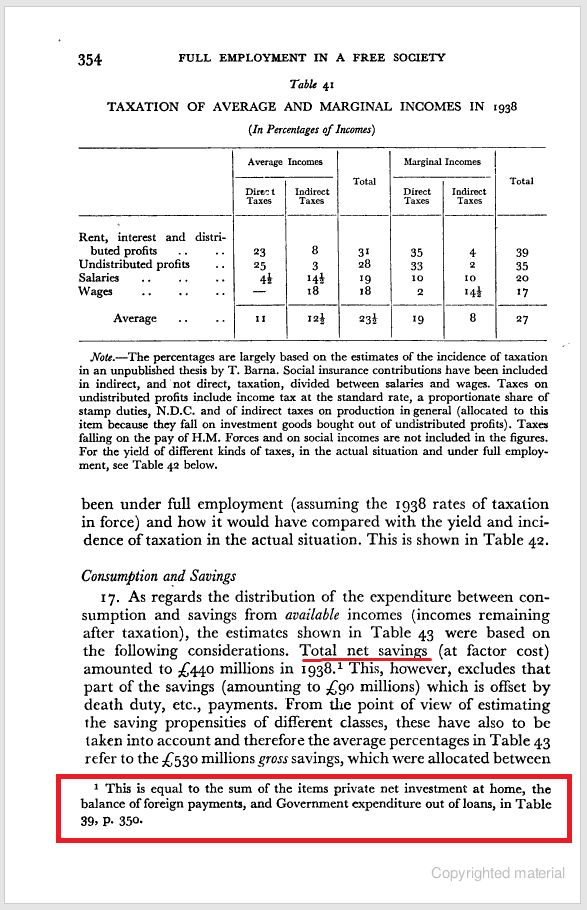
I thought I should share what I found recently about who was to state the sectoral balances identity first – since it comes across as enlightening to say the least. I found the identity in Nicholas Kaldor’s 1944 article Quantitative Aspects Of The Full Employment Problem In Britain. It was published as Appendix C to Full Employment In A Free Societyby William Beveridge.
(If you find the mention of this identity anywhere before, please let me know!)
Here’s a Google Books screenshot of the page:
The article also appears in Kaldor’s Collected Essays, Vol 3 (Chapter 2, pp. 23-82).
The ‘net’ is net of consumption of fixed capital. Also ‘balance of payments’ is used for the current balance (footnote 1, page 28). (In TheScourge Of Monetarism, Kaldor used ‘net saving’ as saving net of investment).
Anthony Thirlwall wrote a biography of Kaldor in 1987 and he mentions that Kaldor kept pushing the implications of the identity in the 1960s (page 251). He managed to convinced some of his colleagues such as Wynne Godley and Francis Cripps and pick up public fights with others such as Richard Kahn.
Wynne Godley recalled how he came to appreciate this identity in his book Monetary Economics with Marc Lavoie. In Background Memories (W.G.) he wrote:
… In 1970 I moved to Cambridge, where, with Francis Cripps, I founded the Cambridge Economic Policy Group (CEPG). I remember a damascene moment when, in early 1974 (after playing round with concepts devised in conversation with Nicky Kaldor and Robert Neild), I first apprehended the strategic importance of the accounting identity which says that, measured at current prices, the government’s budget deficit less the current account deficit is equal, by definition, to private saving net of investment. Having always thought of the balance of trade as something which could only be analysed in terms of income and price elasticities together with real output movements at home and abroad, it came as a shock to discover that if only one knows what the budget deficit and private net saving are, it follows from that information alone, without any qualification whatever, exactly what the balance of payments must be. Francis Cripps and I set out the significance of this identity as a logical framework both for modelling the economy and for the formulation of policy in the London and Cambridge Economic Bulletin in January 1974 (Godley and Cripps 1974). We correctly predicted that the Heath Barber boom would go bust later in the year at a time when the National Institute was in full support of government policy and the London Business School (i.e. Jim Ball and Terry Burns) were conditionally recommending further reflation! We also predicted that inflation could exceed 20% if the unfortunate threshold (wage indexation) scheme really got going interactively. This was important because it was later claimed that inflation (which eventually reached 26%) was the consequence of the previous rise in the ‘money supply’, while others put it down to the rising pressure of demand the previous year …
So the news is that Mark Carney – the Governor of the Bank of Canada will now be the next Governor of the Bank of England.
Wynne Godley would have been happy – had he been alive and known that Carney is perhaps the only central banker to have recognized his foresight. (Carney probably is also the only central bank head to have named some names.)
… Few forecast these events; although, in an outbreak of retrospective foresight, an increasing number now claim they saw it coming. The reality is that among all the banks, investors, academics and policy-makers, only a handful were able to identify ahead of time the causes and potential scale of the crisis. …
with an attached footnote:
Examples include Bill White, formerly of both the Bank of Canada and the Bank for International Settlements; Harvard University’s Ken Rogoff; Nouriel Roubini of New York University; Wynne Godley of Cambridge; and Bernard Connolly of AIG Financial Products.
I recite all this to suggest, not that sovereignty should not be given up in the noble cause of European integration, but that if all these functions are renounced by individual governments they simply have to be taken on by some other authority. The incredible lacuna in the Maastricht programme is that, while it contains a blueprint for the establishment and modus operandi of an independent central bank, there is no blueprint whatever of the analogue, in Community terms, of a central government. Yet there would simply have to be a system of institutions which fulfils all those functions at a Community level which are at present exercised by the central governments of individual member countries.
The counterpart of giving up sovereignty should be that the component nations are constituted into a federation to whom their sovereignty is entrusted. And the federal system, or government, as it had better be called, would have to exercise all those functions in relation to its members and to the outside world which I have briefly outlined above.
That was published 8th October 1992 – exactly 20 years back!
Worth your time if you haven’t read it yet. Even if you have, worth reading it again!
Here’s the link to the full article Maastricht And All That by Wynne Godley.
He has a nice way of giving a short description of pricing in the G&L models:
In my view, the stock-flow and the demand driven (and I should say, the fact that price dynamics is orthogonal to the income flow determination structure) is the essential characteristic of this approach.
—
Also, Simon Wren-Lewis (from Oxford) has a new blog post on the sectoral balances approach – Sector Financial Balances As A Diagnostic Check, where he mentions Martin Wolf’s recent post on Wynne Godley’s approach. He (Wren-Lewis) has been admitting recently that DSGE models are not useful.
In the comments section Simon Wren-Lewis has this to say:
Martin Wolf sent me the following comment, which I am sure others will also find interesting:
“I used sectoral financial balances before the crisis, following Wynne. I argued that what was going on in the US external and household sectors were evidently unsustainable. This allowed me to argue that when the latter’s deficits were eliminated, there would be a recession and a huge fiscal deficit. What I had not expected was that the turnaround in the household sector would trigger a meltdown of the financial system.
“This makes it clear that one has to link the flow sectoral balances to the balance sheets in the economy. In this case, my mistake was not looking closely enough at the balance sheet of the financial sector. Good macroeconomic analysis has to examine the flows and stock meticulously and seek to assess whether the behaviour we see is sustainable. The assumption that private agents cannot make huge mistakes about the sustainability of what they are doing is, in my view, the biggest mistake in macroeconomics.”
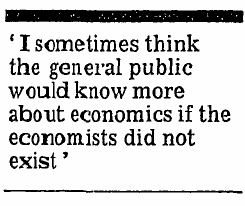
Back to DSGE models. I think they are totally useless. I like this quote by Francis Cripps from an article in The Guardian from 27 Feb 1979: Economists With A Mission:
Martin Wolf who usually writes good articles on macroeconomic developments wrote recently on the sectoral balances approach (which he uses frequently anyway).
… I look at this through the lens of “sectoral financial balances”, an analytical framework learned from the work of the late Wynne Godley. The essential idea is that since income has to equal expenditure for the economy, as a whole, (which is the same things as saying that saving equals investment) so the sums of the difference between income and expenditures of each of the sectors of the economy must also be zero. These differences can also be described as “financial balances”. Thus, if a sector is spending less than its income it must be accumulating (net) claims on other sectors.
The crucial point is that, since sectoral balances must sum to zero, a rise in the deficit of one sector must be matched by an offsetting change in the others. It follows that if the fiscal deficit is increasing, the sum of the surpluses of the other sectors of the economy must be increasing in a precisely offsetting manner.
These are tautologies. But the virtue of this framework is that it forces us to ask what drives what: are, for example, fiscal deficits in the US (or UK) driving the surpluses in other sectors or are the surpluses in the other sectors driving the fiscal deficit? We can obtain answers by examining what behaviour is changing…
and that:
… The idea that the huge fiscal deficits of recent years have been the result of decisions taken by the current administration is nonsense. No fiscal policy changes explain the collapse into massive fiscal deficit between 2007 and 2009, because there was none of any importance. The collapse is explained by the massive shift of the private sector from financial deficit into surplus or, in other words, from boom to bust…
The sectoral balances approach should always be handled with supreme care. There are causalities running in all directions and one needs to ask what brings them to equivalence, what the value of policy instruments are, how is output changing etc.
Although the three balances must always sum to exactly zero, no single balance is more a residual than either of the other two. Each balance has a life of its own, and it is the level of real output that, with minor qualifications, brings about their equivalence. Underlying the main conclusions of our reports is an econometric model in which exports, imports, taxes, and private expenditure are determined as functions of such things as world trade, relative prices, tax rates, and flows of net lending to the private sector. However, neither the knowledge that this is the case nor the perusal of any list of econometric equations will, on its own, impart any intuition as to why output moved as it did over any set period.
It is well known to students of the National Accounts that the surplus of private disposable income over expenditure is equal to the government balance (written as a deficit) plus the current balance of payments (written as a surplus). While these balances are related to one another by a system of accounting identities, each has, to some extent, a life of its own that is reconciled with the other two via the aggregate income flow. The way the balances evolve provides a useful armature around which to organise a narrative account of economic developments, because any one of them is necessarily implied by the other two. Furthermore, the balances may give an early warning that unsustainable processes are taking place, for any high or rising balance implies a change in public, private, or foreign debts, which cannot grow without limit relative to income.
Wynne Godley with his CEPG partner Francis Cripps (from Cambridge Group Sings The Blues, The Guardian, 17 April 1980)
Both Angela Merkel and the German Finance Minister Wolfgang Schäuble have been quoted in the media as saying that they won’t go ahead with the “€-bills” and plans like that in their lifetime! Of course such quotes are incompletely reported and what they mean is that they won’t have a plan such as that without a common fiscal policy.
Of course this didn’t go through because the two German leaders wouldn’t have allowed it in their lifetimes! So what does Germany really want?
To understand this we must first understand that – as argued by Wynne Godley in 1992 – to join a monetary union nations should surrender their sovereignty with this sovereignty being taken over by a supranational authority (which was absent in the Maastricht Treaty):
I recite all this to suggest, not that sovereignty should not be given up in the noble cause of European integration, but that if all these functions are renounced by individual governments they simply have to be taken on by some other authority. The incredible lacuna in the Maastricht programme is that, while it contains a blueprint for the establishment and modus operandi of an independent central bank, there is no blueprint whatever of the analogue, in Community terms, of a central government. Yet there would simply have to be a system of institutions which fulfils all those functions at a Community level which are at present exercised by the central governments of individual member countries.
The counterpart of giving up sovereignty should be that the component nations are constituted into a federation to whom their sovereignty is entrusted. And the federal system, or government, as it had better be called, would have to exercise all those functions in relation to its members and to the outside world which I have briefly outlined above.
Merkel and Schäuble want to move ahead with the full creation of a federation – presumably headquartered in Brussels and they have the task of managing the fiscal decisions for the whole of the Euro Area. Since this institution will run deficits, it is natural that it will finance the difference between expenditure and taxation by issuing bills and bonds (which will be the real €-bonds). Hence the two leaders have qualified their statements but this has been quoted everywhere as some kind of comedy of errors!
The two leaders have the double task of convincing the German politicians and German public on the one hand and politicians from the rest of the Euro Area on the other hand. In the middle of this, they see this plan from Herman Van Rompuy, José-Manuel Barroso, Jean-Claude Juncker and Mario Draghi adding to confusions. The plan from the four EU leaders still has no supranational institution which makes financial decisions for the whole Euro Area but only a special purpose entity presumably retired after 25 years.
The important difficulty in the creation of a supranational institution which will manage the finances of the whole Euro Area (and not any “sinking fund”) is that the current setup is an incomplete one where nations’ governments still have a good amount of power in spite of them having surrendered most of their sovereignty.
While convincing the German citizens may be a hard task, Merkel and Schäuble are facing difficulties also in convincing other European leaders. Other nations do not wish to surrender whatever powers they still have but in the process do not understand what an integration means. Their leaders could have chosen to not join the Euro Area – just like what Mrs Thatcher did for the UK. Now that they have joined it and given it is difficult for any one nation to leave, it is in their best interest to go ahead with the full integration which has a supranational fiscal authority but this comes with surrendering more powers!
As Wynne Godley argued further:
If a country or region has no power to devalue, and if it is not the beneficiary of a system of fiscal equalisation, then there is nothing to stop it suffering a process of cumulative and terminal decline leading, in the end, to emigration as the only alternative to poverty or starvation. I sympathise with the position of those (like Margaret Thatcher) who, faced with the loss of sovereignty, wish to get off the EMU train altogether. I also sympathise with those who seek integration under the jurisdiction of some kind of federal constitution with a federal budget very much larger than that of the Community budget. What I find totally baffling is the position of those who are aiming for economic and monetary union without the creation of new political institutions (apart from a new central bank), and who raise their hands in horror at the words ‘federal’ or ‘federalism’. This is the position currently adopted by the Government and by most of those who take part in the public discussion.
As Jim O’ Neill of Goldman Sachs mentions in a recent interview to Bloomberg, the Germans are open to this but unfortunately, the French have objections to this route.
In the above video (edit: no longer available), O’ Neill (jokingly called Governor O’Neill by Tom Keene of Bloomberg because he is said to be the top man for the post of the chief of the Bank of England when Mervyn King’s term ends soon) argues the Europeans are known to leave it till the last moment – when it’s on the brink. Till then they will continue to muddle. Unfortunately for Merkel and Schäuble, solving short term issues makes the financial market conditions ease substantially, the opposite of what they want, because only when other Euro Area nations are in a lot of trouble will they be ready to accept the German solution. Of course this is a sad way to solve the problem but Schäuble has been quoted in the press saying that the EA needs a crisis to make any progress.
After falling short with her “fiscal compact” on budget discipline, German Chancellor Angela Merkel is pressing for much more ambitious measures, including a central authority to manage euro area finances, and major new powers for the European Commission, European Parliament and European Court of Justice.
She is also seeking a coordinated European approach to reforming labor markets, social security systems and tax policies, German officials say.
Until states agree to these steps and the unprecedented loss of sovereignty they involve, the officials say Berlin will refuse to consider other initiatives like joint euro zone bonds or a “banking union” with cross-border deposit guarantees – steps Berlin says could only come in a second wave.
“Kaldorians” jumped to highlight the serious defects in the European plan for integration when officials were working on the Maastricht Treaty. One of the implicit assumption on which the dogma of “free trade” is pushed is that current account deficits do not matter. The government’s task is to only make markets free in this view. The Euro Area was formed with the highly incorrect notion (among various others) that nations can simply solve their “balance of payments problem” by getting rid of it altogether.
I was reading this article by Ken Coutts and Wynne Godley from 1990 [1] where the authors point to different kinds of arguments put forward by others to defend this position (“current account deficits do not matter” provided markets are made free).
There appear to be six different lines of argument to the effect that the current account deficit can be ignored …
… (v) A different kind of argument makes a comparison between a nation with an external deficit and a relatively poor region within a nation. It is pointed out that there is no balance of payments problem for Scotland or for Northern Ireland and from this it is concluded that as soon as Britain joins a European monetary union its balance of payments ‘problem’ will disappear permanently …
… The argument (v) that a region within a country cannot have a balance of payments ‘problem’ ignores the fact that if a region imports more than it exports its trade deficit is automatically paid for by fiscal transfers.[footnote: Strictly speaking, the fiscal transfers will always exactly compensate for any trade deficit only after allowing for the acquisition of financial assets by the private sector as implied by the ‘New Cambridge’ identity (exports less imports equals net government outlays plus the ‘trade’ deficit). The identity says, of course, nothing whatever about the level of real income and output which trading performance will have generated]. The point may be illustrated by considering an extreme case where a region consumes tradables but cannot produce them at all. In this case there will be a trade deficit exactly equal to imports of tradables, but the flow of government expenditure and net transfers will provide a minimum level of income support and keep life of a kind going without any borrowing at all taking place. If an uncompetitive region were not in receipt of fiscal inflows, its inhabitants would have no alternative but to emigrate or starve. This example illustrates that merely by sharing a common currency with another area, a region or country does not automatically dispose of its balance of payments problems since its prosperity still depends on how successfully it can compete in trade with other areas. The Delors Report itself correctly observes that a monetary union transforms a weakness in the ability to compete successfully from being a balance of payments problem into a regional problem to which there is only likely to be a solution by using the instruments of regional policy.
The movement toward more integration by giving higher powers to the European Parliament was also suggested by Wynne Godley and Marc Lavoie in 2007 [2]:
… Alternatively, the present structure of the European Union would need to be modified, giving far more spending and taxing power to the European Union Parliament, transforming it into a bona fide federal government that would be able to engage into substantial equalisation payments which would automatically transfer fiscal resources from the more successful to the less successful members of the euro zone. In this manner, the eurozone would be provided with a mechanism that would reduce the present bias towards downward fiscal adjustments of the deficit countries.
References
Prosperity and Foreign Trade in the 1990s: Britain’s Strategic Problem, Oxf Rev Econ Policy (1990) 6 (3):82-92. Link
A Simple Model Of Three Economies With Two Currencies, Camb. J. Econ. (2007) 31 (1): 1-23. Link
The crisis has a lot of connections with the way Macroeconomics was done in the 1970s and this interests me a lot. Of course the equally important reason was that Nicholas Kaldor and Wynne Godley were highly involved in the public discussions. Here are some books I collected which have special importance to the Cambridge Economic Policy Group (CEPG):
I could manage to only get used copies of the first two books.
The book has the paper New Cambridge Macroeconomics And Global Monetarism – Some Issues In The Conduct Of U.K. Economic Policy, by Martin Fetherston and Wynne Godley and comments by others such as Alan Blinder – which I mentioned in the post Debt Monetization. The book is also available from Wiley but you have to pay $500+ for it!
This one got the title right – it wasn’t Keynesianism versus Monetarism. It was New Cambridge versus Keynesianism versus Monetarism.
The following book by Peter Kenway was first published in 1994 but was republished recently because the crisis has deep roots with debates in the 1970s!
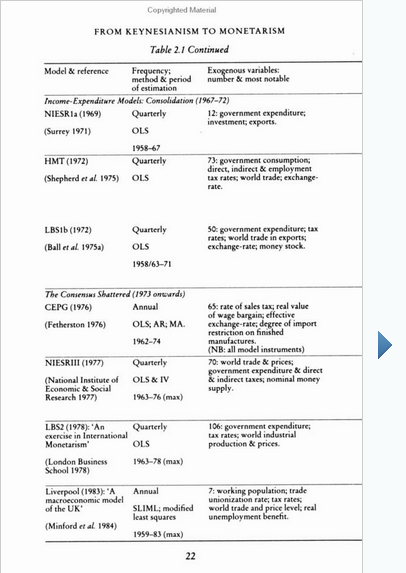
It has nice discussions about the various types of income/expenditure models of the 1970s in the UK with a lot on the CEPG. It gives nice lists of all models – some of them here (via amazon.com preview):
Here’s a short autobiography by Wynne Godley (written around 1999) on how he dissented from the profession. Here’s a Google Books preview from the book A Biographical Dictionary of Dissenting Economists edited by Philip Arestis and Malcolm C. Sawyer
click to view on Google Books
I like this:
… I had extraordinary difficulty in understanding, not the sentences, but what real life state of affairs mainstream ‘neoclassical’ macroeconomics could possibly be held to be describing. I went through the standard textbooks on macroeconomics and then back to the underlying professional literature (the locus classicus being, as I now see it, Modigliani. 1944 and 1963). I taught myself how to draw the diagrams and solve the equation systems, but for years could not make any connection between these and the real world as I knew it…
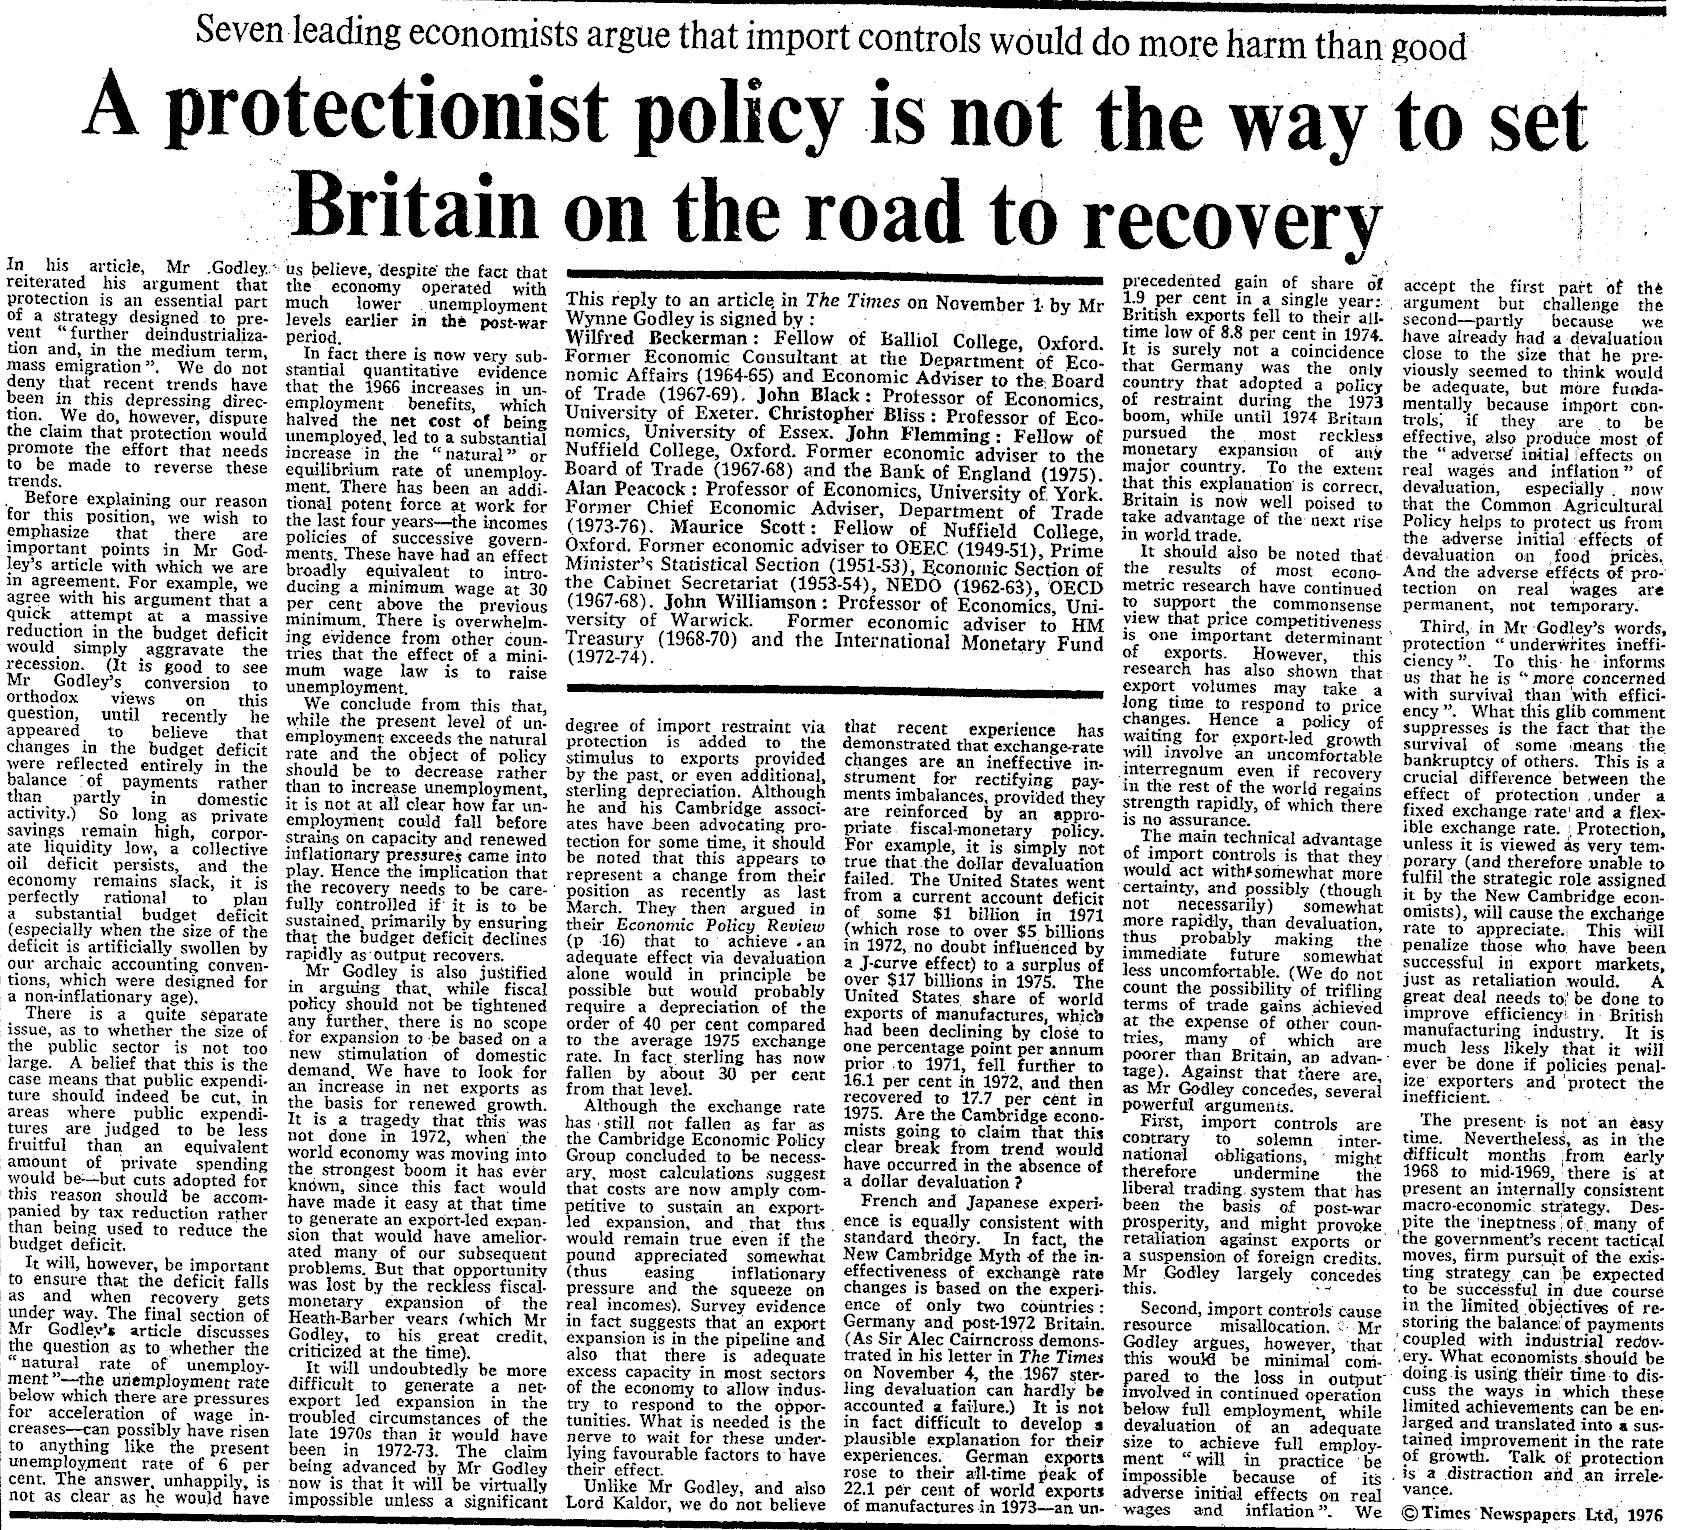
One of the things which made Godley dissenting was the proposal to control imports as the paper title suggests:
(click for link to the journal)
This was met with huge hostility as a Times article (from the late 70s) shows. Economists confused it as “selective protectionism”:
Nouriel Roubini tweets about Trichet’s plan to save the Euro Zone and wonders about sovereignty:
click to view the tweet on Twitter
Two things:
My guess is Trichet’s plan involves a Euro Area institution setting fiscal policy. Trichet’s plan seems to involve some set of technocrats taking control of fiscal policy of a weak nation and then deflating domestic demand and hence not solving anything at all or making it worse. Here it is – clear from the following:
For the European Union, a fully fledged United States of Europe where nation states cede a large chunk of fiscal authority to the federal government appears politically unpalatable, Trichet said.
An alternative is to activate the EU federal powers only in exceptional circumstances when a country’s budgetary policies threaten the broader monetary union, he said.
Secondly, Nouriel Roubini thinks it “undermines national sovereignty” but the Euro Area nations had given this up long back! So while Euro Area nations surrendered sovereignty long back, Trichet’s plan involves removing more powers from governments without the possibility of those nations receiving fiscal equalization in return!
Trichet’s plan hence has a “central government” with no fiscal authority! There was no sovereignty to begin with and no institution taking up the sovereignty either.
The Man Who Saw Through The Euro had a profound way of looking at how economies function. Wynne Godley already understood in 1992 that by joining the Euro Area, nations surrender their sovereignty. In his article 20 years back Maastricht And All That, Godley said:
But there is much more to it all. It needs to be emphasised at the start that the establishment of a single currency in the EC would indeed bring to an end the sovereignty of its component nations and their power to take independent action on major issues.
and that:
… I recite all this to suggest, not that sovereignty should not be given up in the noble cause of European integration, but that if all these functions are renounced by individual governments they simply have to be taken on by some other authority. The incredible lacuna in the Maastricht programme is that, while it contains a blueprint for the establishment and modus operandi of an independent central bank, there is no blueprint whatever of the analogue, in Community terms, of a central government.
and also that:
If a country or region has no power to devalue, and if it is not the beneficiary of a system of fiscal equalisation, then there is nothing to stop it suffering a process of cumulative and terminal decline leading, in the end, to emigration as the only alternative to poverty or starvation.
If we are to proceed creatively towards EMU, it is essential to break out of the vicious circle of ‘negative integration’— the process by which power is progressively removed from individual governments without there being any positive, organic, all-European alternative to transcend it. The nightmare is that the whole country, not just the countryside becomes at best a prairie, at worst a derelict area.
If a government (outside monetary unions) can make a draft at the central bank, why do rating agencies rate governments’ creditworthiness?
In this post, I will attempt to describe the dynamics of defaults and restructurings by going through some monetary economics of open economies.
Carmen Reinhart and Kenneth Rogoff wrote a book in 2009 titled This Time Is Different: Eight Centuries Of Financial Folly or simply This Time Is Different arguing that governments do indeed default – both in debt denominated in the domestic and foreign currencies. They blame the public debt and the government for the public debt – hence giving the innuendo that governments across the planet should attempt to cut public debt by tight fiscal policies. This is an illegitimate conclusion – on which I will say more below.
At another extreme are the Chartalists who argue that the government cannot “run out of money” and hence fiscal policy has no monetary constraints. Sometimes they qualify this statement by saying that the currency they are discussing are “sovereign currencies”. Now, there are various definitions of what a sovereign currency is but it is frequently pointed out by them that nations who have seen restructuring of government debt did not have a “sovereign currency” – because the currency is either pegged or fixed or it is the case that the government had a lot of debt in foreign currency which presumably allows defaults/restructuring of government debt in the domestic currency as well. The motivation behind this is Milton Friedman’s idea that nations should freely float their currencies in international markets and that markets will clear and that the State intervention in the currency markets can only make things worse. Hence Reinhart/Rogoff don’t prove them wrong – according to them – since the situations are supposedly different.
We will see that while there is some truth to it, the notion of a “sovereign currency” is highly misleading. Such intuitions are coincident with the incorrect notion that indebtedness to foreigners (in domestic currency) is just a technical liability and there’s nothing more to that!
Here’s S&P’s article on the methodology it uses to assign ratings on governments: Standard & Poor’s – Sovereign Government Rating And Methodology. One can see the importance it gives to the external sector. However, S&P does not provide a mechanism on how a government will finally end up defaulting. The purpose of this post is to look into this.
Before this let us make a connection between the public debt and the net indebtedness of a nation. Most people in the planet confuse the two. The former is the debt of the government whereas the latter is the (net) indebtedness of the nation as a whole. This is the net international investment position (adjusting for traditional settlement assets such as gold) with the sign reversed. This can be obtained by consolidating all the sectors of an economy and the consolidation involves (for example) netting of the assets of the domestic private sector held abroad and also its gross indebtedness to the rest of the world.
So one can think of two extremes:
Japan – with a high public debt of about 195% of gdp (includes just the central government debt), while being a net creditor of the world. It’s NIIP is about 50% of gdp (data source: MoF, Japan)
Australia – with a low public debt of 18% of gdp and NIIP of minus 59% of gdp.
So in the case of Japan, while the government is a huge debtor, the nation as a whole is a creditor, whereas in the case of Australia, it is the opposite. So the rating agencies get it wrong or opposite!
Let us first assume a closed economy. The greatest starting point in analyzing economies is the sectoral balances approach. For a closed economy it is:
NAFA = DEF
where NAFA is the Net Accumulation of Financial Assets of the private sector and DEF is the government’s budget deficit. If the private sector wants to accumulate a lot of financial assets, and the government wants to run the economy near full employment, the public debt will be higher, the higher the propensity to save, for example. (This is not as straightforward as presented here but can be shown in a simple stock-flow consistent model). So unlike what neoclassical economists think, the level of public debt is somewhat irrelevant. Neither does the government has too much trouble in financing its debt because the public debt is the mirror image of the private sector net financial asset position.
Now let us take the case of an open economy. The sectoral balances identity now is
NAFA = DEF + CAB
A deficit in the current account implies an increase in the net indebtedness to foreigners. Unless the markets miraculously clear with the exchange rate adjusting to bring the CAB in balance, a deficit in the current account implies the nation as a whole has to attract foreigners to finance this deficit i.e., via a lower NAFA or higher DEF. In the long run, the private sector is accumulating financial assets (or has small positive NAFA) and the whole of the current account balance is reflected in the public sector balance.
So the debate fixed vs floating doesn’t help too much. A relaxation of fiscal policy may spill over into higher imports with the public debt and the net indebtedness to foreigners keeps rising forever to gdp. Hence nations typically have to curb growth to bring the current account into balance.
This is theory. So let’s look at an open economy mechanism of an event of default by the government as a story.
In the following, I will use the phrase “pure float” instead of the dubious terminology “sovereign currency”.
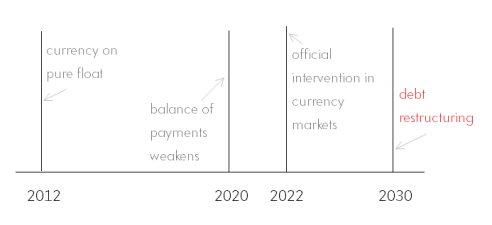
Here’s the simplest model:
In the above, a nation with its currency on a pure float and with zero official sector liabilities in foreign currencies has a somewhat weak external position in 2012. Now, according to some of the Neochartalist arguments this nation can’t default on its government debt. However this is a wrong conclusion as the scenario above hightlights. In the scenario constructed, the balance of payments position weakens over the years (and I have mentioned that roughly in 2020 it weakens). In 2022, foreigners are no longer willing to finance the debt. This may be due to a capital flight or due to the inability of the banking system to maintain a low net open position in foreign currency. The depreciation of the domestic currency isn’t sufficient to clear the fx markets and the official sector (either the central bank or the government’s treasury) necessarily has to intervene in the foreign exchange markets by issuing debt denominated in foreign currency. The government is then acting as the borrower of the last resort and the objective is to use the proceeds to partially have more foreign exchange reserves and/or to sell the foreign currency proceeds from the debt issuance to clear the fx markets. The government is then left with a net liability position in the foreign currency. Soon the external situation worsens to the point requiring official foreign help – such as from the IMF – which promises to help and requires a restructuring of the debt both in domestic and foreign currencies.
Free marketers have a blind belief in the markets and the theories are built on the assumption that markets always clear. The recent crisis has highlighted that this isn’t the case. Even for the case of Australia – whose currency can be considered closed to being pure float – has had issues in the external sector and the Reserve Bank of Australia had to borrow in US dollars from the Federal Reserve (via swap lines) to help Australian banks meet their foreign currency funding needs during the crisis.
Of course the above is not typical but to prevent the external vulnerability to go out of control, governments keep domestic demand low and a lot of times, they over-do this.
The point of the exercise is to prove that it is not meaningless to think of nations becoming bankrupt in whichever situation one can think of and it doesn’t help to laugh at the rating agencies and make fun of them – possibly with the exception for the case of Japan. Statements such as “government with a sovereign currency cannot become bankrupt” are simply misleading. In the above, the Chartalists would argue that the currency was not sovereign and they were not wrong about the default but the currency was sovereign in their own definition in 2012!
Here are some comments on some nations.
Japan: As mentioned above, Japan is a net creditor of the rest of the world and partially as a consequence of that, most of the Japanese government’s debt is held internally. The rating agencies are aware of this but in spite of this continue to make comments on the creditworthiness of the Japanese government. It is possible that residents may transfer funds abroad for unknown reasons (which the raters for some reason suspect) but it may require just a minor interest rate hike to prevent this from happening. Japan has a relatively strong external situation and hence has no issues in financing its government debt.
Canada: Nick Rowe of WCI mentioned to me on his blog that worrying about the balance of payments constraint is like “beating a dead horse” – citing the example of Canada which has floated its currency and it seems has no trouble with its external sector. But this ignores other things in the formulation of the problem. Canada is an advanced nation and an external situation which is not weak. However, a growth of the nation much faster than the rest of the world will lead to a worsening of the external situation. To some extent the nation’s external situation has been the result of its relatively better competitiveness of exporters compared to its propensity to import and a demand situation which either as a conscious attempt of demand management of the government or by pure fluke has helped its external situation remain non-vulnerable.
United States: The US dollar is the reserve currency of the world and slowly over time, the United States has turned from being a creditor of the rest of the world to becoming the world’s largest debtor nation. (Again not due to its public debt but because of its net indebtedness to foreigners). The US external sector is a great imbalance and any attempt to get out of the recession by fiscal policy alone will worsen its external situation leading to a crash at some point. S&P is right! So to come out of the depressed state, the nation has to complement fiscal expansion with improvement of the external situation such as by (and not restricted to) asking trading partners to not revalue their currencies. Still for some reasons bloggers at the “New Economic Perspectives” think that
… Bernanke also knows that the US has infinite ability to finance these fiscal components, that there is no solvency issue and that the policy rate and both ends of the yield curve are under the direct control of the Fed.
Back to This Time Is Different. While Reinhart and Rogoff’s analysis of government debt may be useful, their conclusions can be destructive for the world as a whole. The domestic private sector of a nation needs continuous injection from outside so that it can run surpluses in general and tightening of fiscal policies will lead to a depression. Global imbalances is crucial in understanding the nature of this crisis (and not public debt alone) and even coordinated attempts to reflate economies may provide only a temporary relief. Since failure in international trade restricts the growth of nations and their attempts to reach full employment, what the world needs is an entirely different way to run the economies under managed trade with fiscal expansion. Ideas of “free trade” such as that outlined here by Alan Blinder simply help some classes of society at the expense of others because it relies on the “market mechanism” which has failed over and over again.
This brings me to “sovereignty”. As argued, the concept “sovereign currency” is almost vacuous (except highlighting the problems of the Euro Area) but sovereignty as argued by Wynne Godley in his great 1992 article Maastricht And All That and by Anthony Thirlwall in the same year on FT (my post on it here Martin Wolf Pays A Generous Tribute To Anthony Thirlwall) definitely have great importance. Some of Thirwall’s concepts of economic sovereignty in the article were: the ability to protect and encourage strategic industries, the possibility of designing systems of managed trade to even out payments imbalances, the ability to protect against certain countries with persistent surpluses, differential taxes which discriminate in favour of the tradeable goods sector.